Nordex Group has raised its full-year 2026 EBITDA margin guidance to 11.5–12.5%, up from 8.0–11.0%, after preliminary third-quarter results came in above expectations. All other elements of the forecast are unchanged.
The Hamburg-based turbine maker expects third-quarter EBITDA of about EUR 278 million, against EUR 136 million a year earlier, which equates to a margin of 12.7% (Q3 2025: 8.0%). Preliminary sales are put at roughly EUR 2,187 million, compared with EUR 1,706 million in the third quarter of 2025. The figures are unaudited.
Nordex attributes the result to higher margins in its service business and strong performance in project execution. It also said risks assumed in the earlier project forecast did not materialise to the extent expected. Free cash flow for the quarter is expected at EUR 379 million (Q3 2025: EUR 149 million), and cash and equivalents stand at EUR 2,327 million, up from EUR 1,929 million at the end of 2025. The company expects free cash flow to remain positive in the fourth quarter.
The remaining guidance is unchanged: group sales of EUR 8.2–9.0 billion, a working capital ratio below minus 9%, and capital expenditure of about EUR 200 million. CEO José Luis Blanco said strong project execution and higher service profitability had given the company a very good starting position for the final quarter.
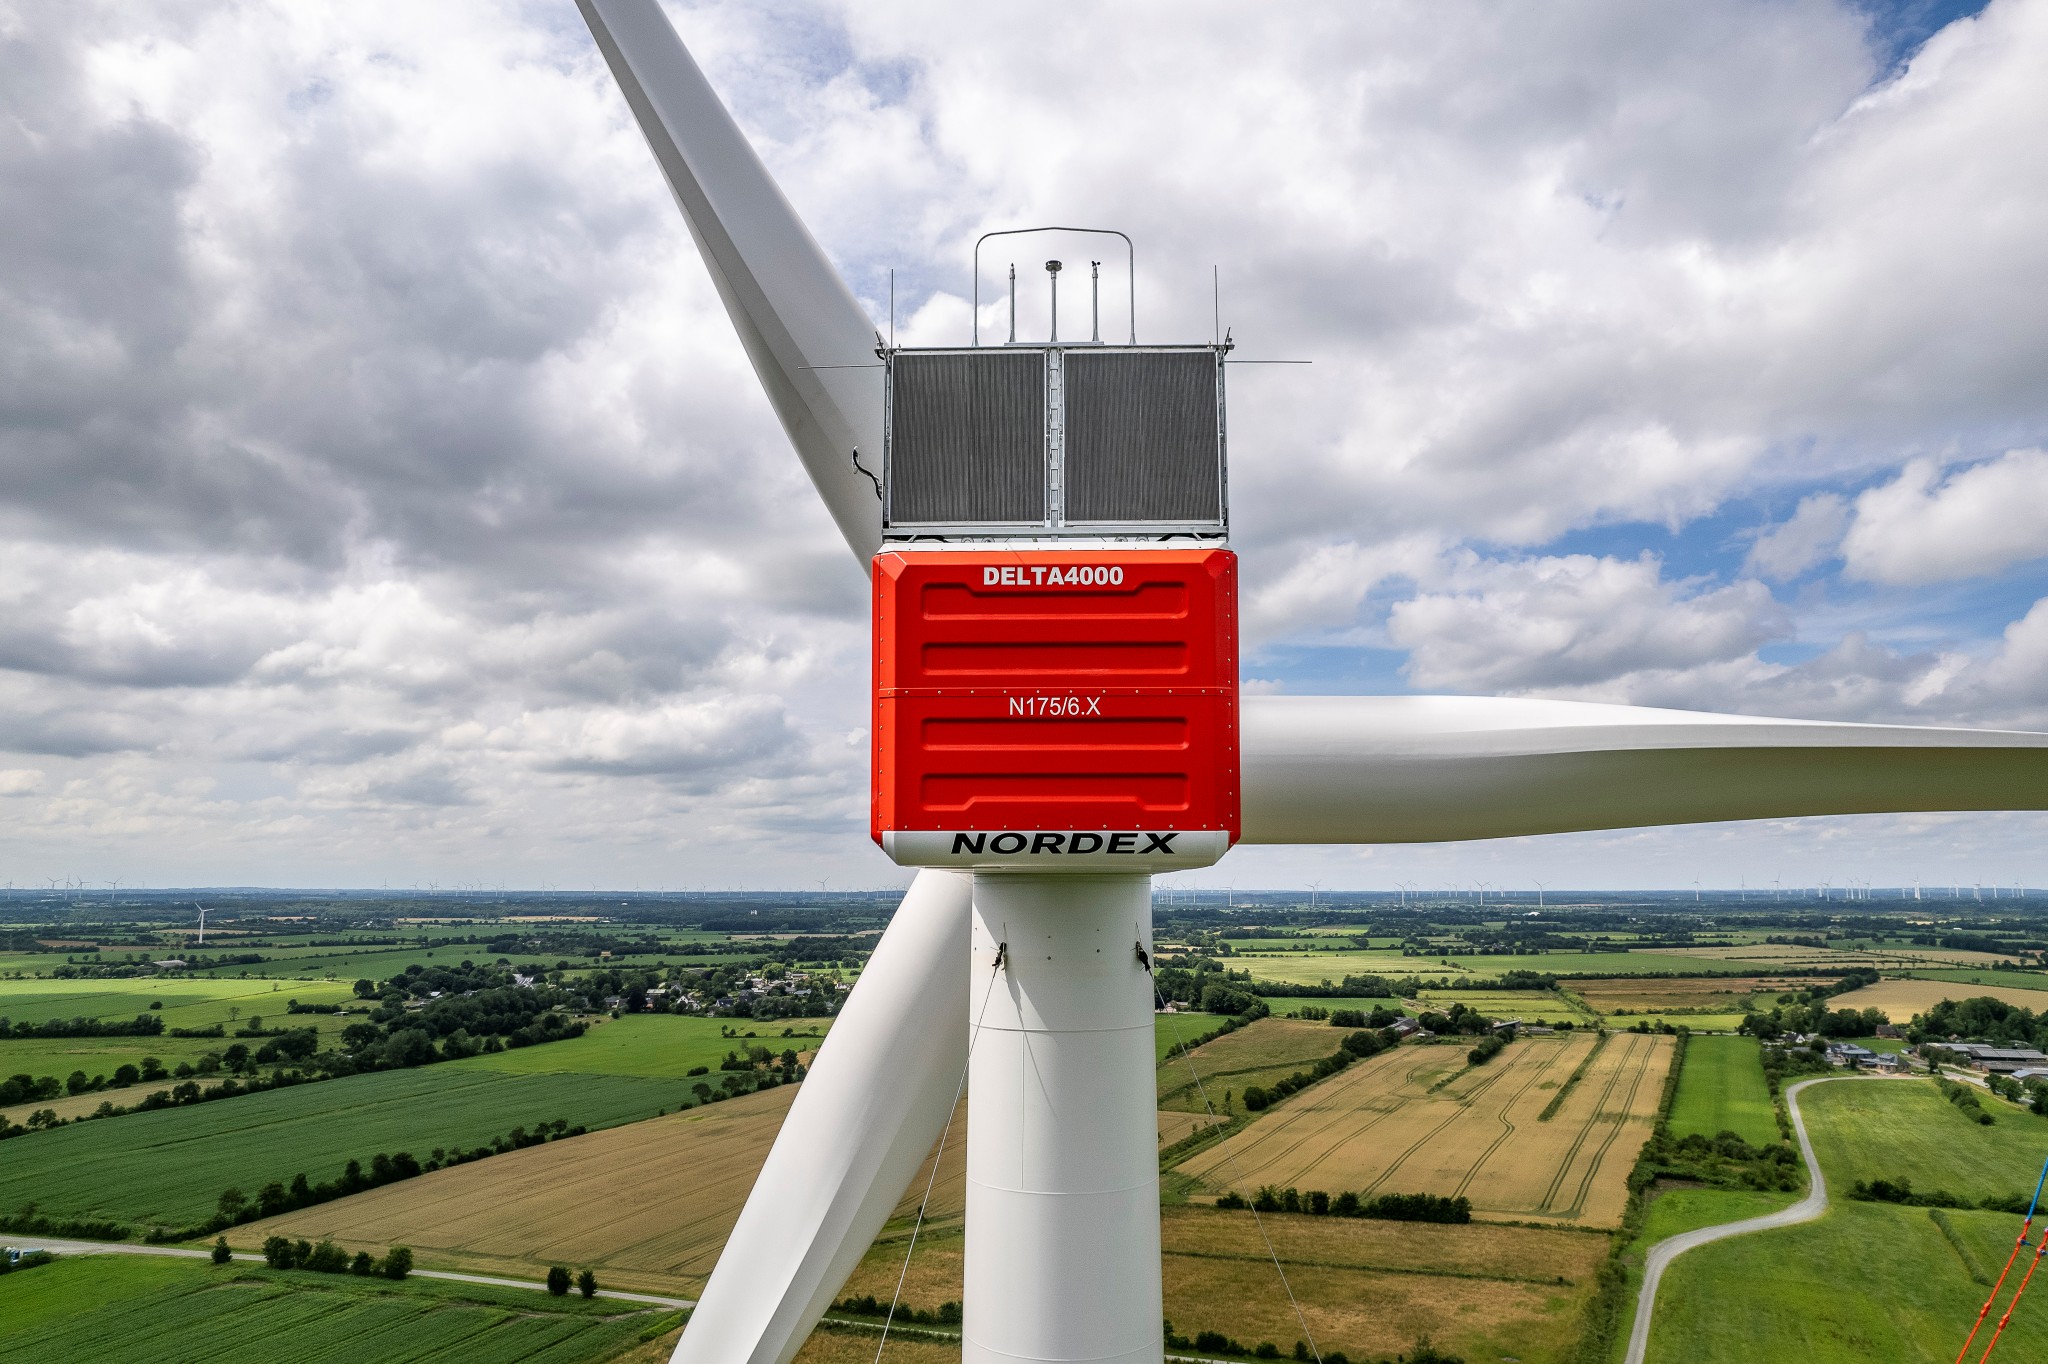
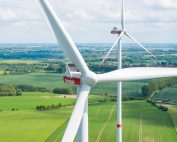
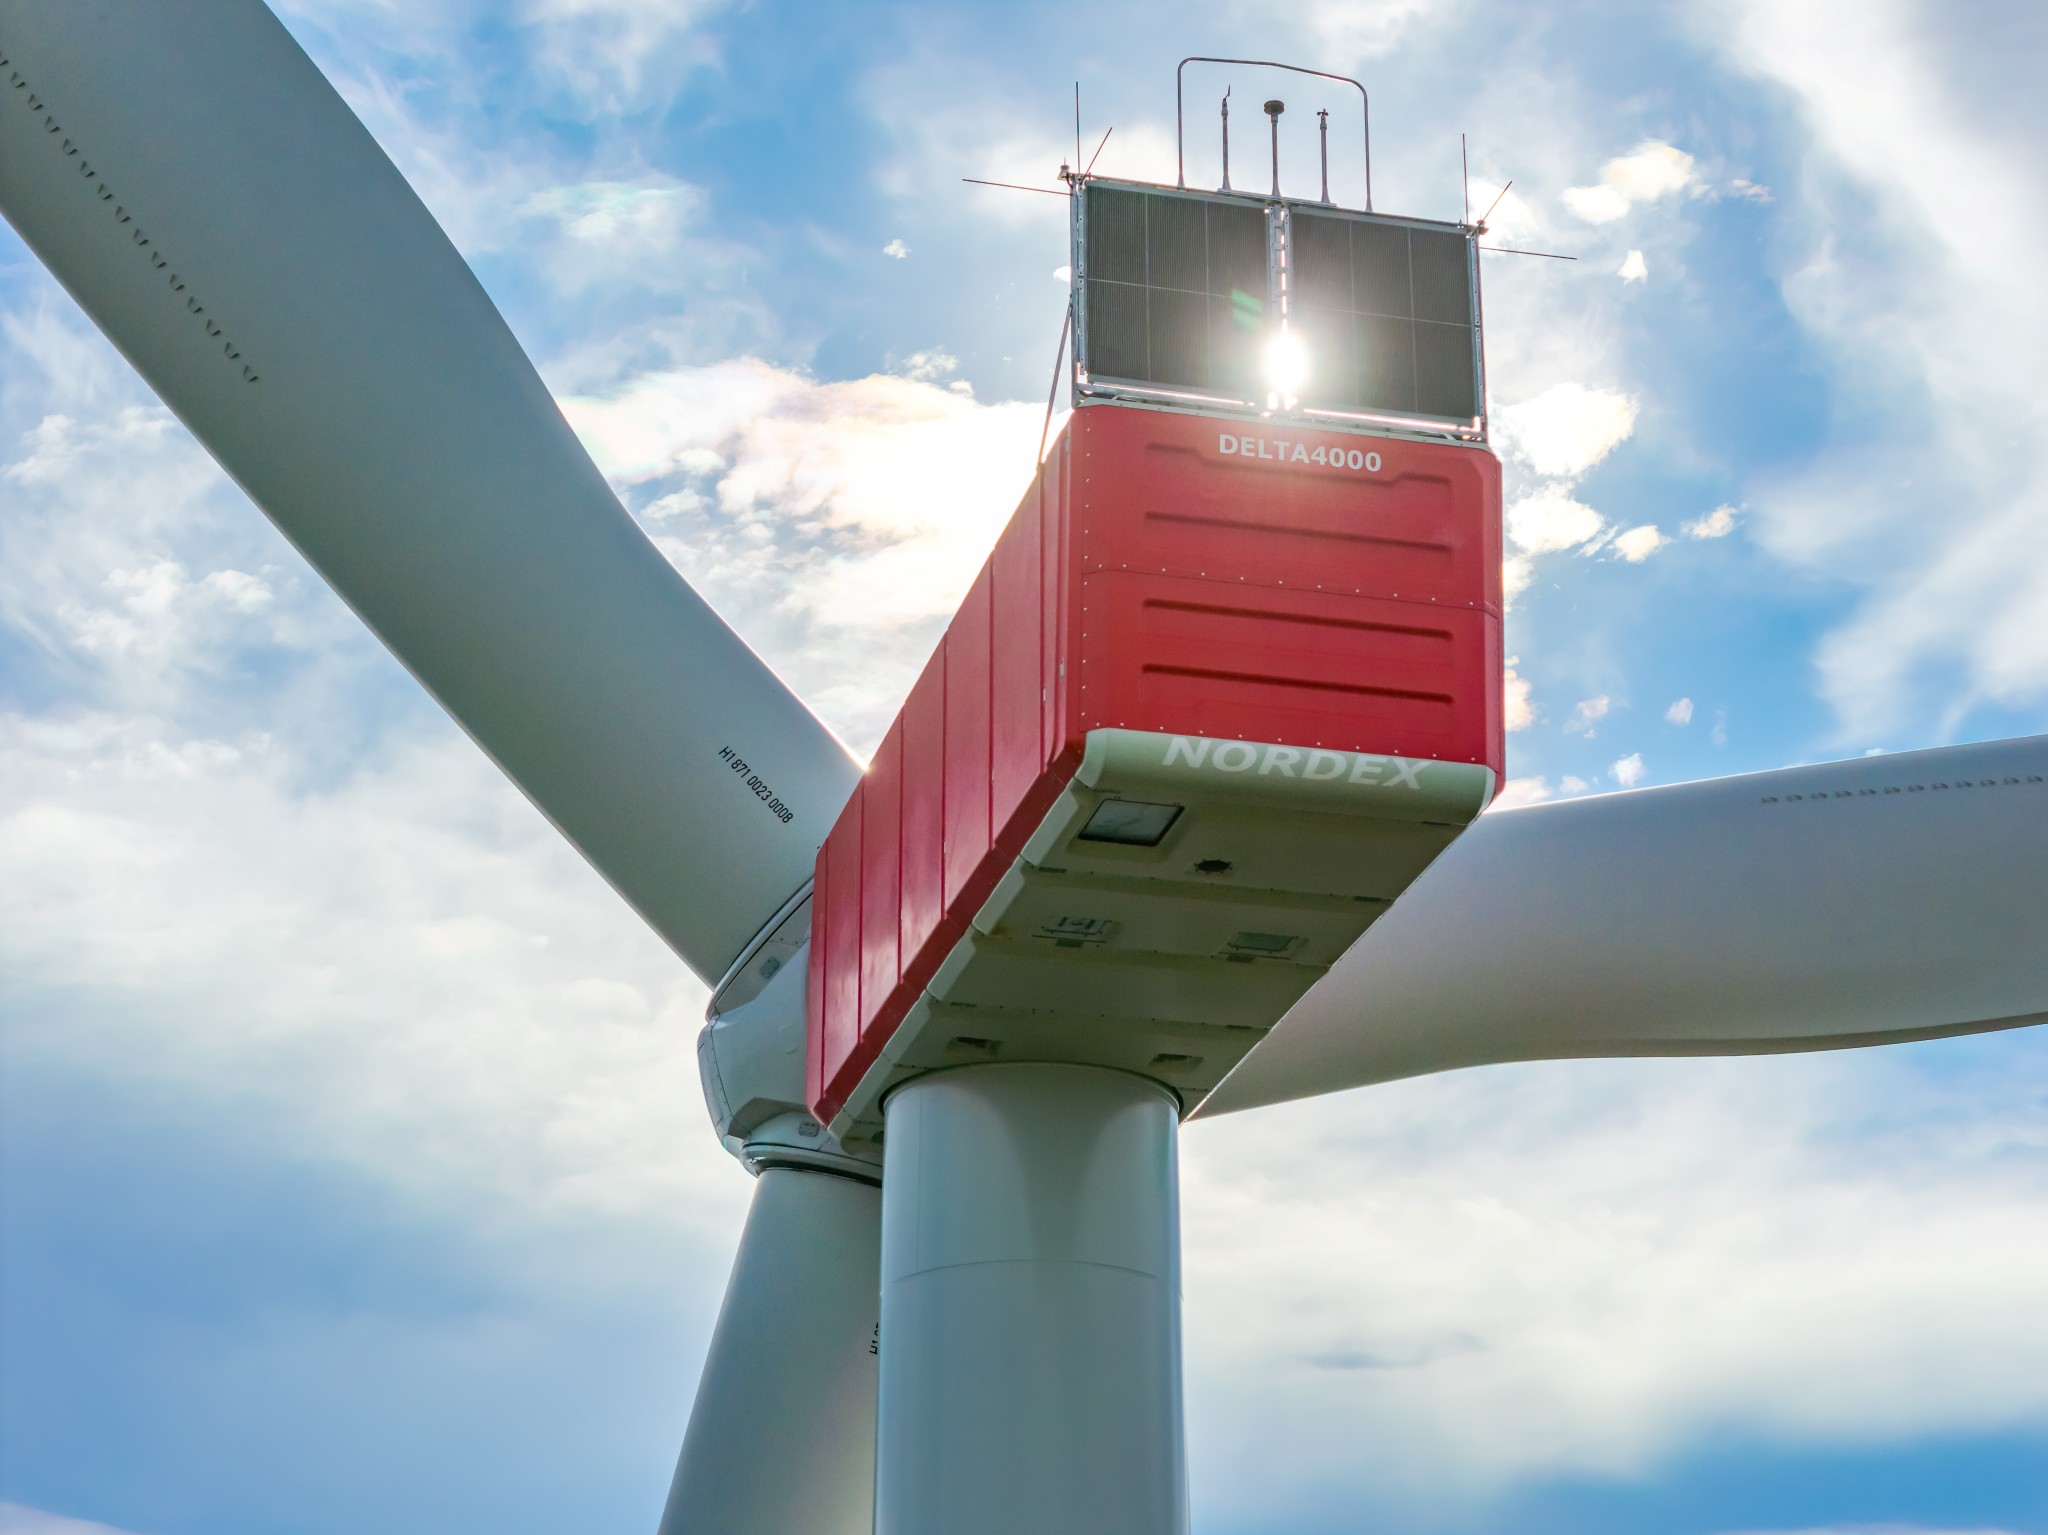
Nordex, which focuses on onshore turbines in the 4 to 7 MW-plus classes, is an established supplier to Germany and the wider Baltic Sea region. It will publish full third-quarter results on 5 November 2026.